FSA — Use It or Lose It Before 31 Dec 2026 (Grace Period vs Rollover)
 DollarLedger Team
- 14 Nov, 2026
Every December, the same quiet loss happens in millions of American paycheques: money set aside in a health Flexible Spending Account (FSA) simply disappears. An FSA lets you pay medical, dental and vision costs with money not included in your income — but unlike a Health Savings Account (HSA), the balance does not roll over on its own. The IRS calls health FSAs “use-it-or-lose-it” plans (IRS Publication 969). What you do not spend by year end is forfeited to your employer — unless your plan offers one of two exceptions. Which exception your plan offers changes everything — and most people never check. All figures were checked on November 13, 2026.
Caption: Photo: The money in your FSA was set aside for exactly this — prescriptions, glasses and dental care. Spend it before it vanishes. (Photo: Pexels)
What You Will Learn
- The three plan designs — and how to find out which one is yours
- The 2026 numbers: the $3,400 limit and the $680 carryover
- Grace period vs carryover — which one saves more
- Smart last-minute ways to spend the balance
- Claim deadlines and next year’s election
Step 1: Find your plan’s rule first
What to do: Before you spend a dollar or book an appointment, find out which of the three designs your employer’s FSA uses.
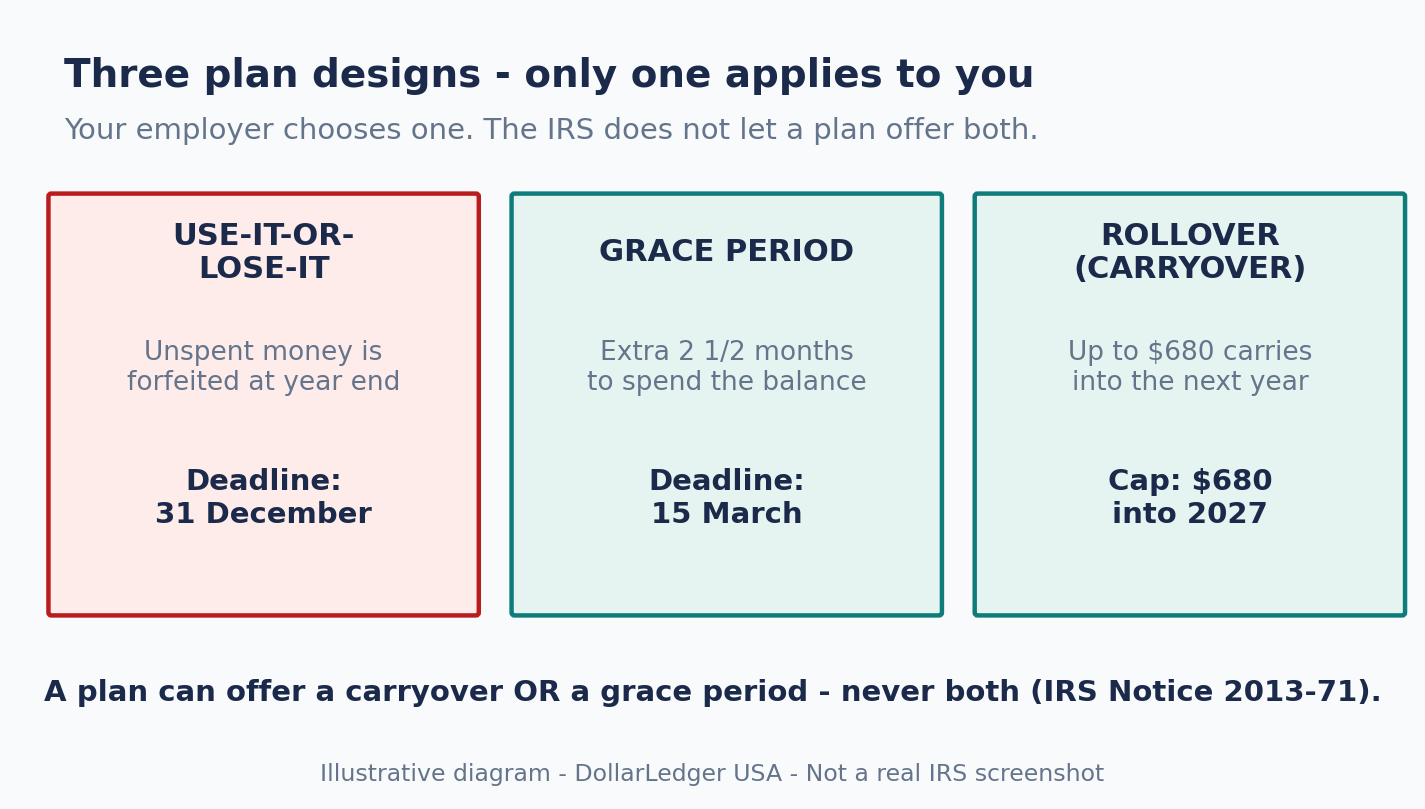
How: There are only three possibilities. Some plans are strict use-it-or-lose-it: every unspent dollar is forfeited at year end. Some offer a grace period of up to two and a half months to spend last year’s balance. Others offer a carryover, letting a capped amount roll forward. A plan cannot offer both (IRS Publication 969, Notice 2013-71), and your employer need not offer either. Find the rule in your benefits portal or Summary Plan Description, or ask HR.
Example: Two co-workers each have $500 left. One has a carryover plan and keeps it all; the other has a strict use-it-or-lose-it plan and loses it all. Same balance, opposite outcomes.
Common mistake: Assuming your plan has a grace period because a friend’s does. Every employer chooses separately.
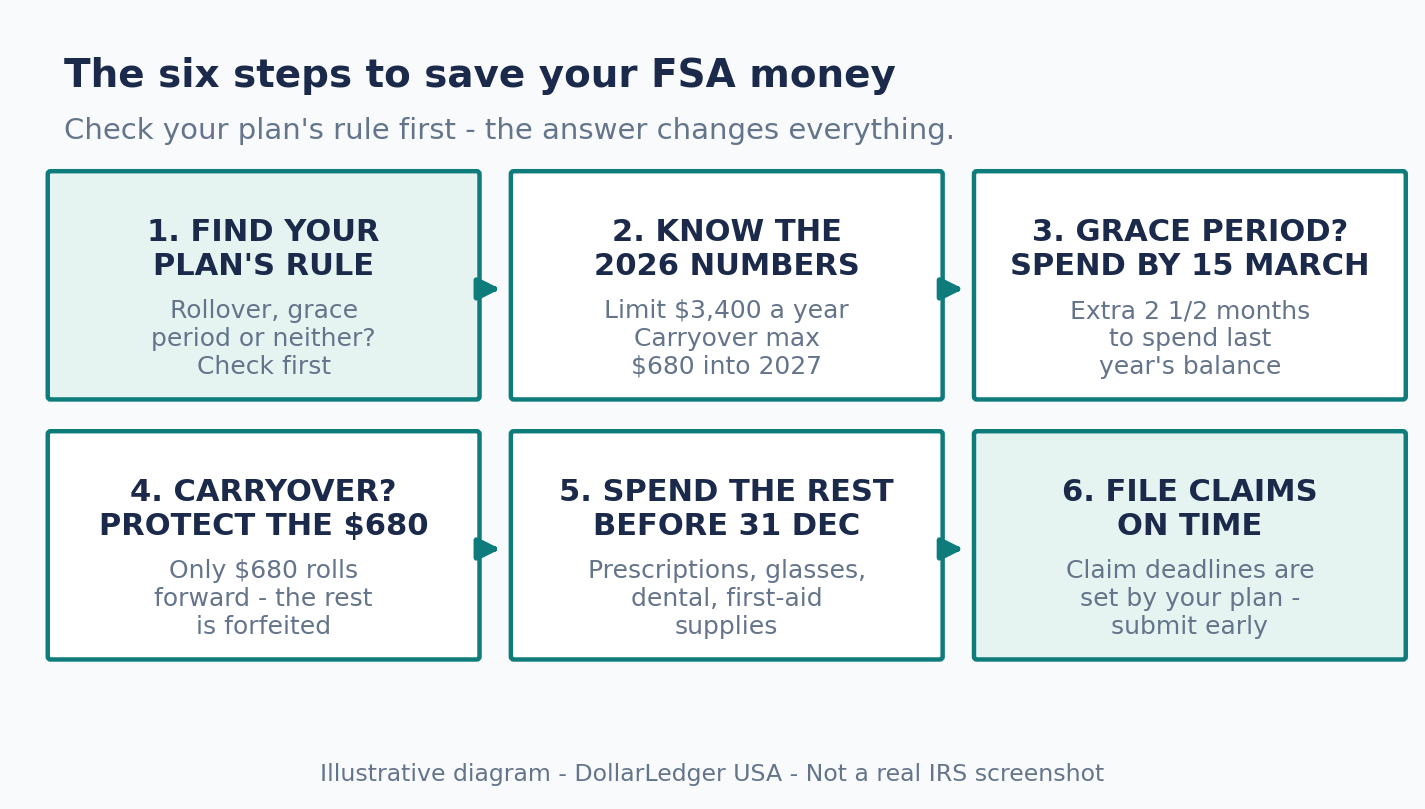
Caption: Illustrative diagram - The six steps to save your FSA money before the deadline. NOT a real IRS screenshot.
Step 2: Know the 2026 numbers — $3,400 in, $680 carries over
What to do: Learn the two figures that govern your FSA in 2026, so you can do the maths on your own balance.
How: In 2026, the IRS caps health FSA contributions at $3,400, up $100 from $3,300 in 2025 (IRS news release IR-2025-103, Revenue Procedure 2025-32). If your plan permits a carryover, at most $680 of unused 2026 money can roll into 2027 — up $20 from $660 in 2025. That $660 is the 2025 figure. The carryover is capped at 20% of the contribution limit, so the two move together. Your employer may set a lower cap. And the carryover does not count against next year’s limit: $680 plus a full $3,400 election gives you up to $4,080 in 2027.
Example: You have $900 left in a carryover plan: $680 rolls into 2027, $220 is forfeited. With only $680 left, the whole balance carries over.
Common mistake: Planning around $660 because that was last year’s figure. The 2026 carryover is $680.
Caption: Photo: New glasses or contact lenses are a classic year-end FSA spend — if your plan covers them. (Photo: Pexels)
Step 3: If you have a grace period — spend by 15 March
What to do: If your plan offers a grace period, use the extra time — but treat 15 March as a hard deadline.
How: A grace period gives you up to two and a half months after the plan year ends to spend last year’s balance on new qualified medical expenses. For a calendar-year plan, that deadline is 15 March. Unlike a carryover, there is no dollar cap: the whole balance can be spent. The expense must be incurred during the grace period — a February doctor’s visit or January glasses count — and anything still unspent when it closes is forfeited. The grace period is about spending, not claiming: your plan may set a separate, earlier claim deadline.
Example: You have $1,200 left and a grace period. Book a dental cleaning and an eye exam in January and refill prescriptions in February, and the full $1,200 can be used. With a carryover, only $680 would survive.
Common mistake: Treating the grace period as extra time to decide. Appointments book up in January.
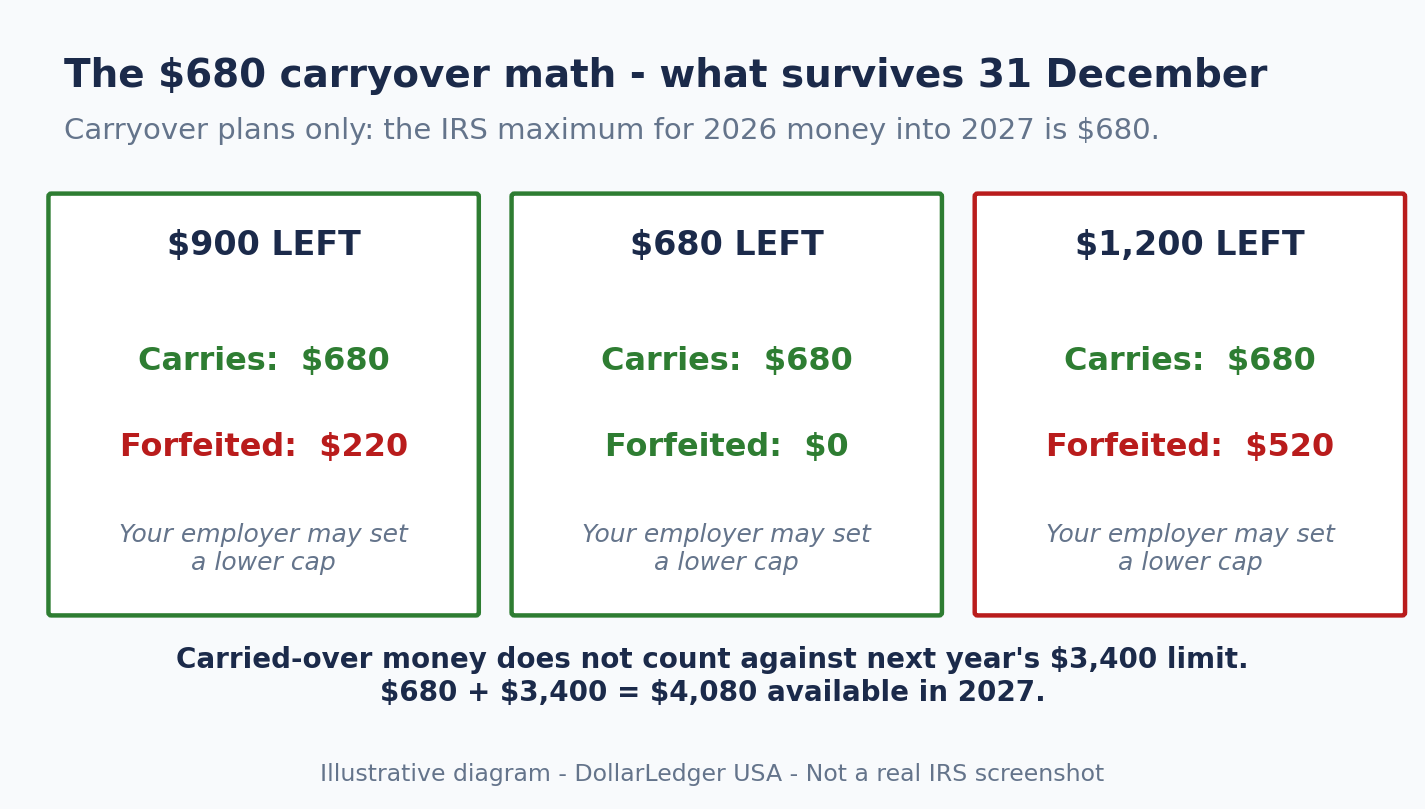
Caption: Illustrative diagram - The $680 carryover math: what survives 31 December. NOT a real IRS screenshot.
Step 4: If you have a carryover — protect the $680
What to do: Treat $680 as safe and spend everything above it before 31 December.
How: The carryover is automatic once your plan offers it: the first $680 rolls into the next year and is available from 1 January. But every dollar above $680 is still forfeited, so the job is to spend down to $680, not to zero. Check your balance today, subtract $680, and that is your December spending target. Your employer may have set a lower cap — $500, say — so that lower figure is your safe amount. Carried-over money does not reduce next year’s contribution (IRS Publication 969), so a full $3,400 election for 2027 on top of it is allowed.
Example: Your balance is $1,200. Spend $520 on a dental filling and new glasses in December, and $680 rolls into 2027. Spend nothing, and $520 vanishes on 1 January.
Common mistake: Thinking the carryover saves everything. It saves at most $680.
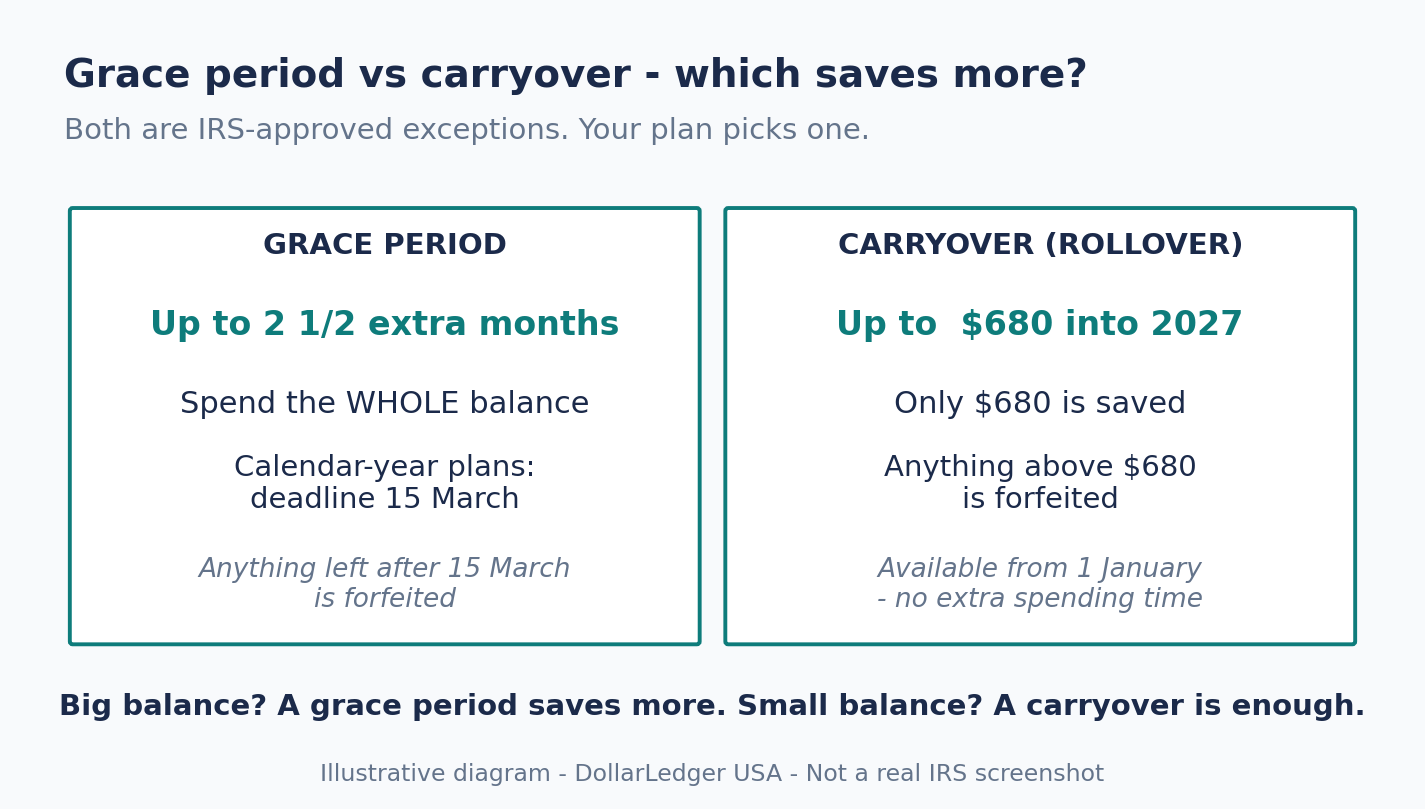
Caption: Illustrative diagram - Grace period vs carryover: which saves more? NOT a real IRS screenshot.
Step 5: Spend the rest on eligible care
What to do: Use the remaining balance on qualified medical expenses you genuinely need — and check your plan’s eligible list before you buy.
How: IRS Publication 502 defines qualified medical expenses as costs of diagnosis, cure, mitigation, treatment or prevention of disease. The most useful year-end spends are prescriptions you already take, new glasses or contact lenses, dental work you have been putting off, an eye exam, and first-aid supplies. Over-the-counter medicine and menstrual care products also count (IRS Publication 969). Your plan’s own list is what matters. The expense must be incurred before your deadline — the appointment or purchase date, not the claim date. And do not buy things you do not need just to use the money: a $200 purchase you would never have made is still $200 gone, even pre-tax.
Example: A $180 eye exam, $250 glasses and a $90 prescription refill is $520 — exactly the amount above the $680 carryover in Step 4.
Common mistake: Buying vitamins or a gym membership and expecting reimbursement. General health does not count (IRS Publication 502).
Caption: Photo: Dental work you have been putting off is one of the best year-end uses of FSA money. (Photo: Pexels)
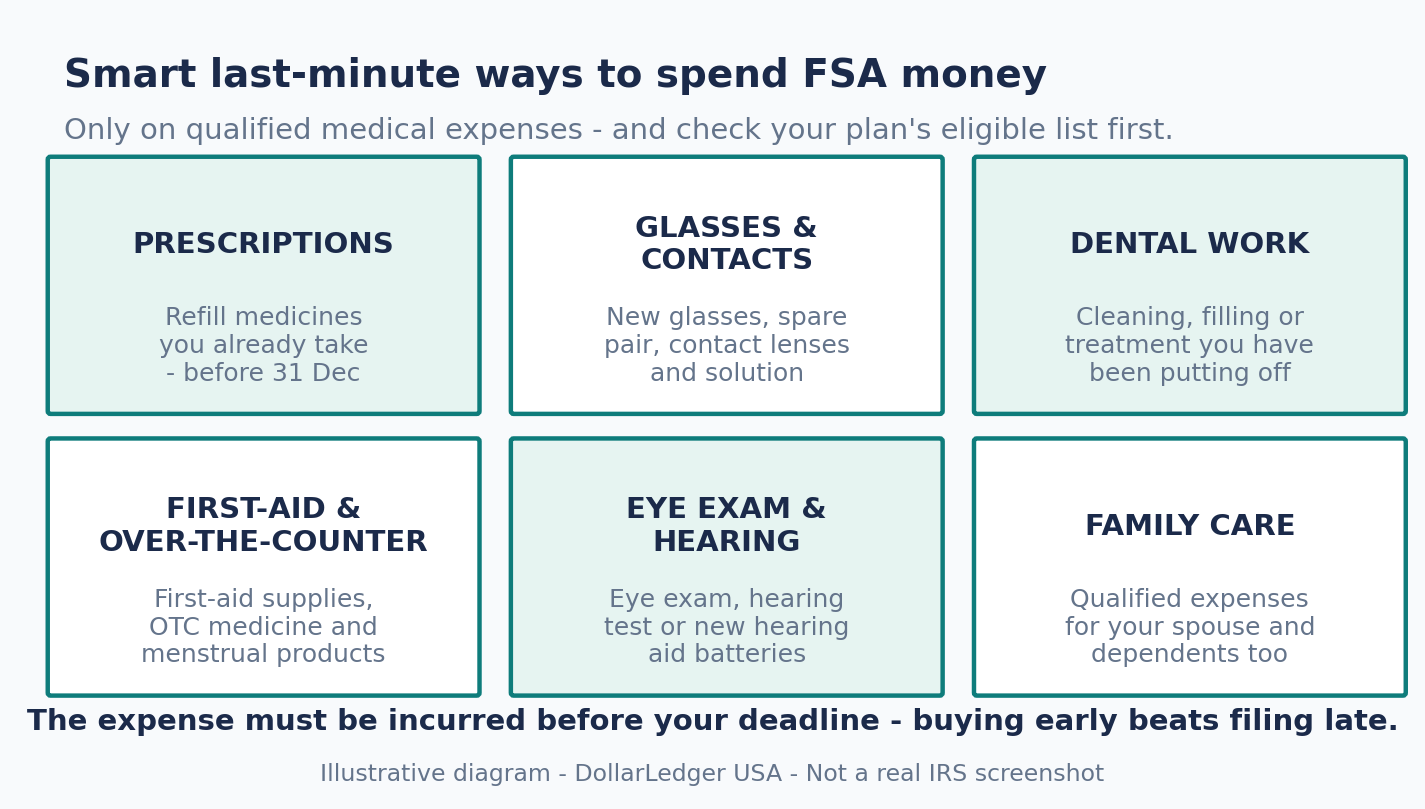
Caption: Illustrative diagram - Smart last-minute ways to spend FSA money. NOT a real IRS screenshot.
Step 6: File claims on time — and set next year’s election right
What to do: Submit every claim before your plan’s deadline, then choose next year’s contribution so this December does not repeat.
How: Your plan sets its own claim deadline, and it can fall before 31 December — some allow 90 days after the expense, others a fixed date in the new year. File as you spend and keep every receipt. If your FSA uses a debit card, keep receipts: the administrator can ask for proof. Then elect an amount you can realistically spend: lower it if you lost money this year, raise it slightly if you ran out in October — within the $3,400 cap. For the bigger picture, read our HSA vs FSA in 2026 guide, and if you are choosing next year’s cover, see our health insurance open enrolment guide for 2026.
Example: You spend $400 on glasses on 20 December but file in March, after your plan’s 28 February claim deadline. The money is gone though the expense was eligible.
Common mistake: Assuming the spending deadline and the claim deadline are the same date. They are often different.
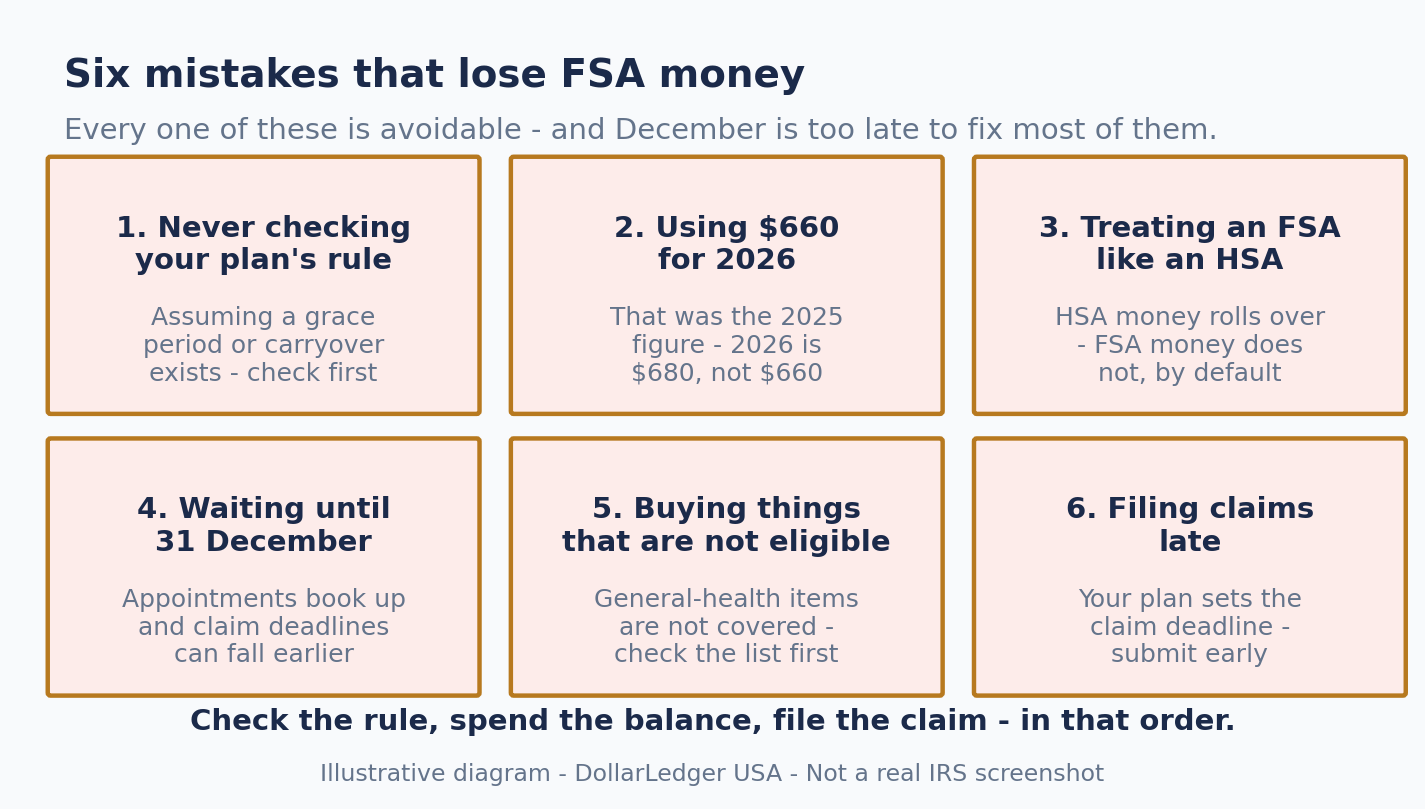
Caption: Illustrative diagram - Six mistakes that lose FSA money. NOT a real IRS screenshot.
Checklist
- Plan rule found — rollover, grace period or neither — from the benefits portal or HR.
- Balance checked; amount above $680 (or your plan’s cap) calculated.
- Grace period deadline noted — 15 March for calendar-year plans.
- Appointments booked — dentist, eye exam, prescriptions refilled.
- Eligible list checked before buying anything.
- Claims filed as you spend, receipts kept.
- Next year’s election set to an amount you can spend.
FAQ
What happens to unused FSA money at the end of the year?
By default it is forfeited to your employer. The only exceptions are a grace period of up to two and a half months or a carryover of up to $680 for 2026, if your plan offers one.
Can my plan offer both a grace period and a carryover?
No. A plan that adopts a carryover for health FSAs is not permitted to also provide a grace period, and vice versa (IRS Publication 969, Notice 2013-71). Your employer must pick one — or neither.
How much FSA money can I carry over into 2027?
Up to $680 of unused 2026 money, if your plan offers a carryover. Your employer may set a lower cap. The $660 figure online is the 2025 carryover.
Is an FSA the same as an HSA?
No. HSA money stays until you use it and rolls over yearly; FSA money is use-it-or-lose-it without a grace period or carryover. See our HSA vs FSA in 2026 guide.
Can I use FSA money for my family’s medical costs?
Yes — for yourself, your spouse and your dependents, as long as the expense is eligible under your plan. Check your plan’s list first.
Sources
- IRS, Publication 969 — Health Savings Accounts and Other Tax-Favored Health Plans (opened live November 13, 2026): https://www.irs.gov/publications/p969
- IRS, IRS releases tax inflation adjustments for tax year 2026 (IR-2025-103, Revenue Procedure 2025-32) (opened live November 13, 2026): https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill
- IRS, Publication 502 — Medical and Dental Expenses (opened live November 13, 2026): https://www.irs.gov/publications/p502
All figures checked November 13, 2026, against IRS Publications 969 and 502 and news release IR-2025-103 (Revenue Procedure 2025-32).
Disclaimer: For education only, not financial, tax or investment advice. Confirm your plan’s rule and the current figures with your benefits administrator and on irs.gov.