Best High-Yield Savings Accounts in USA 2026
 DollarLedger Team
- 02 Nov, 2026
Your savings account might be earning almost nothing, and you would never know unless you check. The national average savings rate in the USA is just 0.38% APY, so $10,000 in an average account earns about $38 in a whole year. The best high-yield savings accounts pay around 4% APY or more right now: same $10,000, same safety, about $440 a year instead of $38. Online banks cost less to run, so they pay more interest. This guide lists the best high-yield savings accounts in the USA for 2026, checked November 2, 2026, with the real conditions for each rate.
Photo: Saving starts small — a high-yield account makes every dollar work harder. (Photo: Pexels)
What You Will Learn
- What APY means, and why it beats the interest rate
- The best high-yield savings accounts in the USA right now, with their conditions
- How much more $10,000 earns at 4.40% APY vs 0.38% APY
- How FDIC and NCUA insurance protect your money up to $250,000
- How to pick the right account in six simple steps
Step 1: Understand APY before you compare rates
What to do: Learn the one number that makes comparisons fair: APY.
How: APY stands for annual percentage yield. It is the real return you earn in one year, including compounding. It is the only number you need for a fair comparison. The interest rate is just the headline number.
Example: An account paying 4.40% APY earns $440 on $10,000 in one year. At 0.38% APY, the same money earns $38. That $402 difference is the whole point.
Common mistake: Chasing the biggest number in an ad without checking whether it is an APY or a promotional rate.
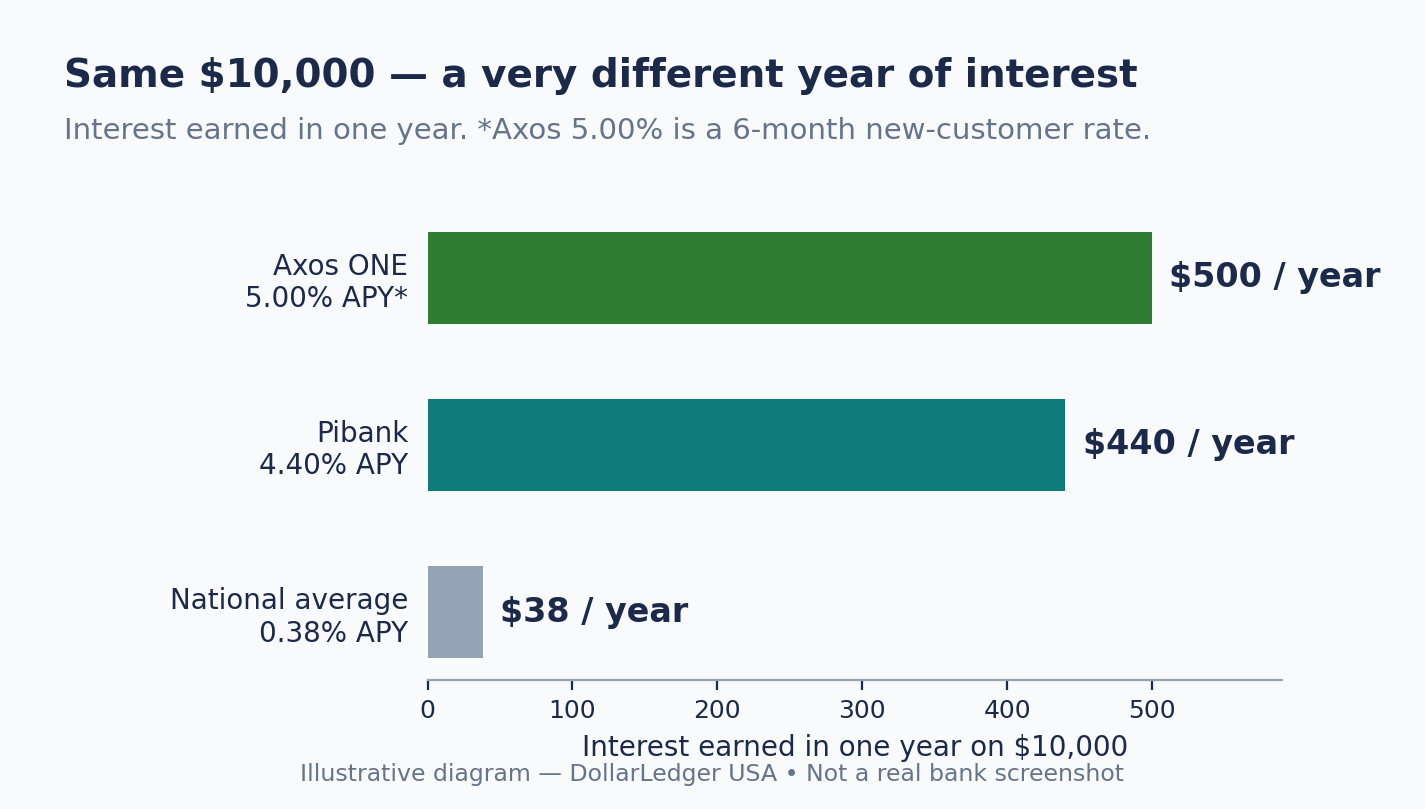
Illustrative diagram — Same $10,000, a very different year. NOT a real bank screenshot.
Step 2: See what compounding does to your money
What to do: Understand compounding — the reason a high APY wins by more than it looks.
How: When a bank compounds monthly, it adds interest to your balance every month. Next month, you earn interest on that interest too. Most high-yield accounts compound daily or monthly.
Example: Take $1,000 at 4.40% for one year: simple interest earns $44.00, monthly compounding earns $44.90. Small over a year, but over 10 years it turns into $551.96 instead of $440.00.
Common mistake: Thinking 90 cents does not matter. On $10,000 over five years, the difference is about $100.
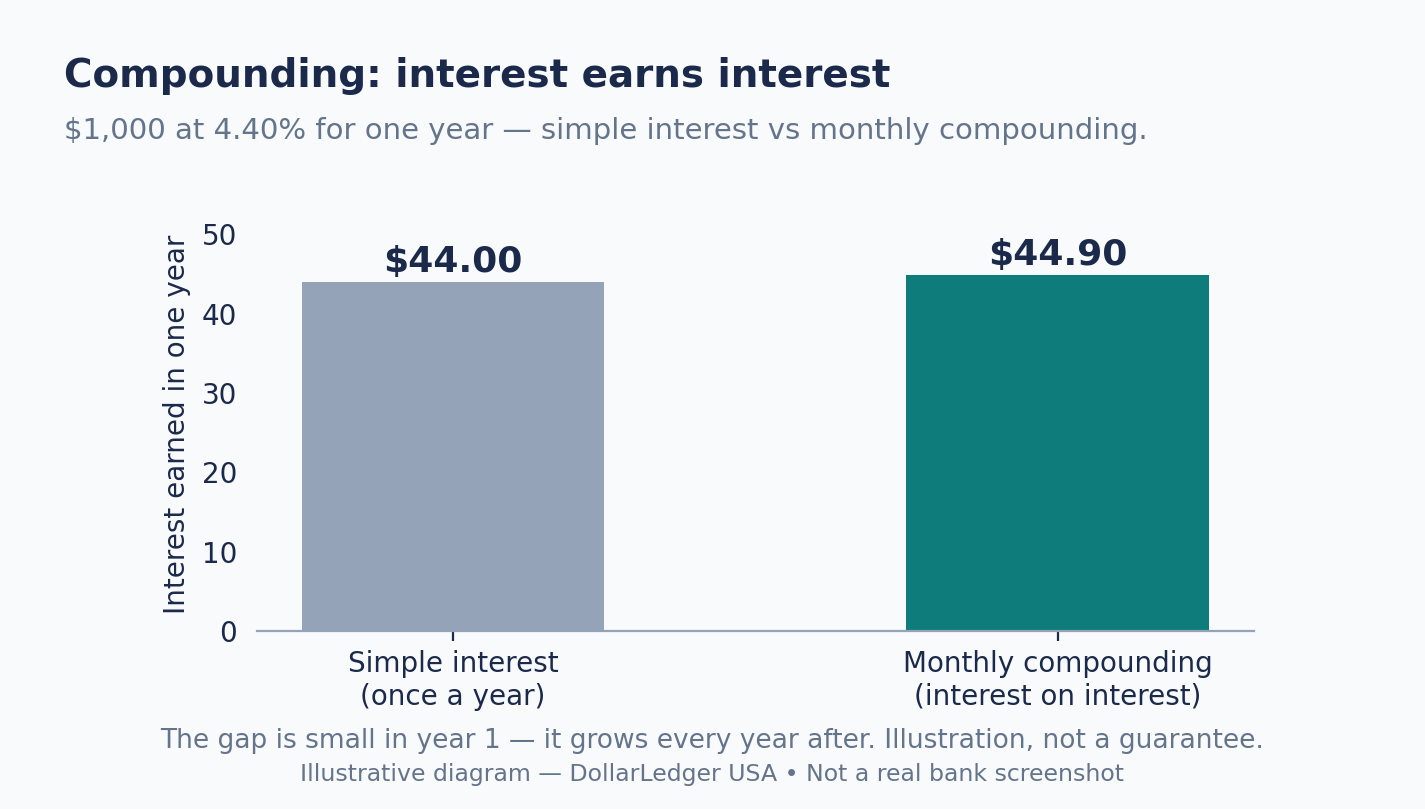
Illustrative diagram — Interest earns interest. NOT a real bank screenshot.
Step 3: Compare the best rates right now
What to do: Compare the highest APYs, then read the conditions.
How: The best high-yield savings accounts in the USA, checked November 2, 2026. National average is 0.38% APY (FDIC). All rates below are variable and can change. Check the conditions before you choose:
- Axos ONE — up to 5.00% APY. New customers, first 6 months. Needs $1,500 in Axos checking plus $1,500 in direct deposit each month.
- GO2bank — up to 4.50% APY. On vault balances up to $5,000; checking must be active.
- St. Mary’s Credit Union — 4.50% APY. On balances up to $50,000.
- Pibank — 4.40% APY. No minimum deposit and no special requirements.
- Elevault — 4.34% APY. No minimum, on balances up to $500,000.
- Peak Bank — 4.27% APY. On balances up to $500,000.
- EverBank — 4.20% APY. No minimum deposit.
Example: At Pibank, $10,000 at 4.40% APY earns about $440 in a year, with no minimums. At Axos ONE, the same $10,000 earns about $500 — but only for six months, and only if you hold $1,500 in their checking account and receive $1,500 in direct deposits each month.
Common mistake: Picking the highest number without reading the cap. GO2bank pays 4.50% only up to $5,000 in the vault; above that, the rate drops. Always ask what balance the rate covers.
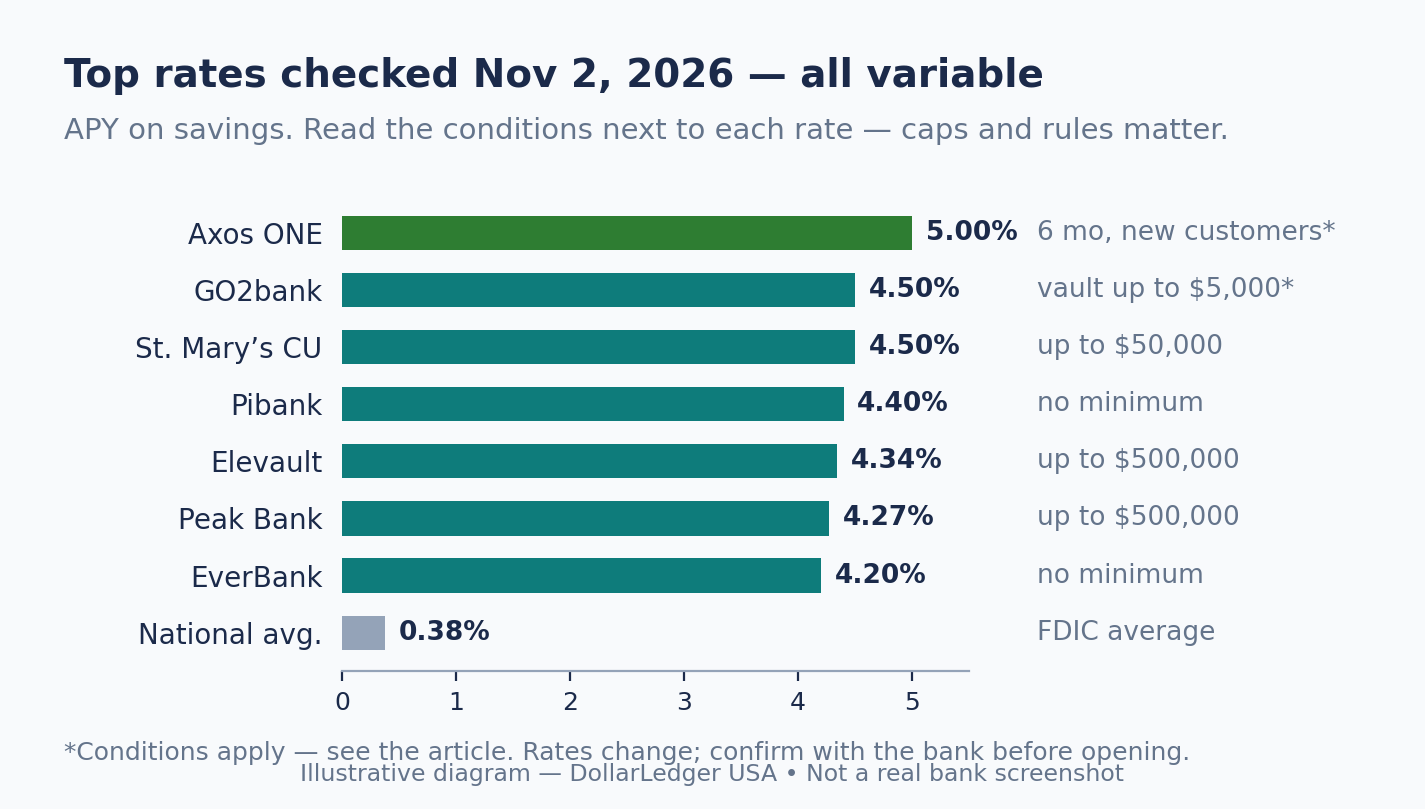
Illustrative diagram — Top rates, Nov 2, 2026. All rates are variable. NOT a real bank screenshot.
Photo: Comparing rates takes ten minutes on a laptop. Check the conditions, not just the headline number. (Photo: Pexels)
Step 4: Check safety — FDIC and NCUA insurance
What to do: Before opening any account, confirm your money is insured.
How: The FDIC insures deposits up to $250,000 per depositor, per insured bank, per ownership category. Credit unions have the same protection from the NCUA. If the bank fails, your money is safe up to that limit.
Example: You have $200,000 in a single account at one FDIC-insured bank: all of it is insured. Add a second bank and you have $250,000 of cover at each bank.
Common mistake: Assuming every money app is a bank. Some apps are not banks. Your money is only protected when the app holds it at an FDIC-insured bank.
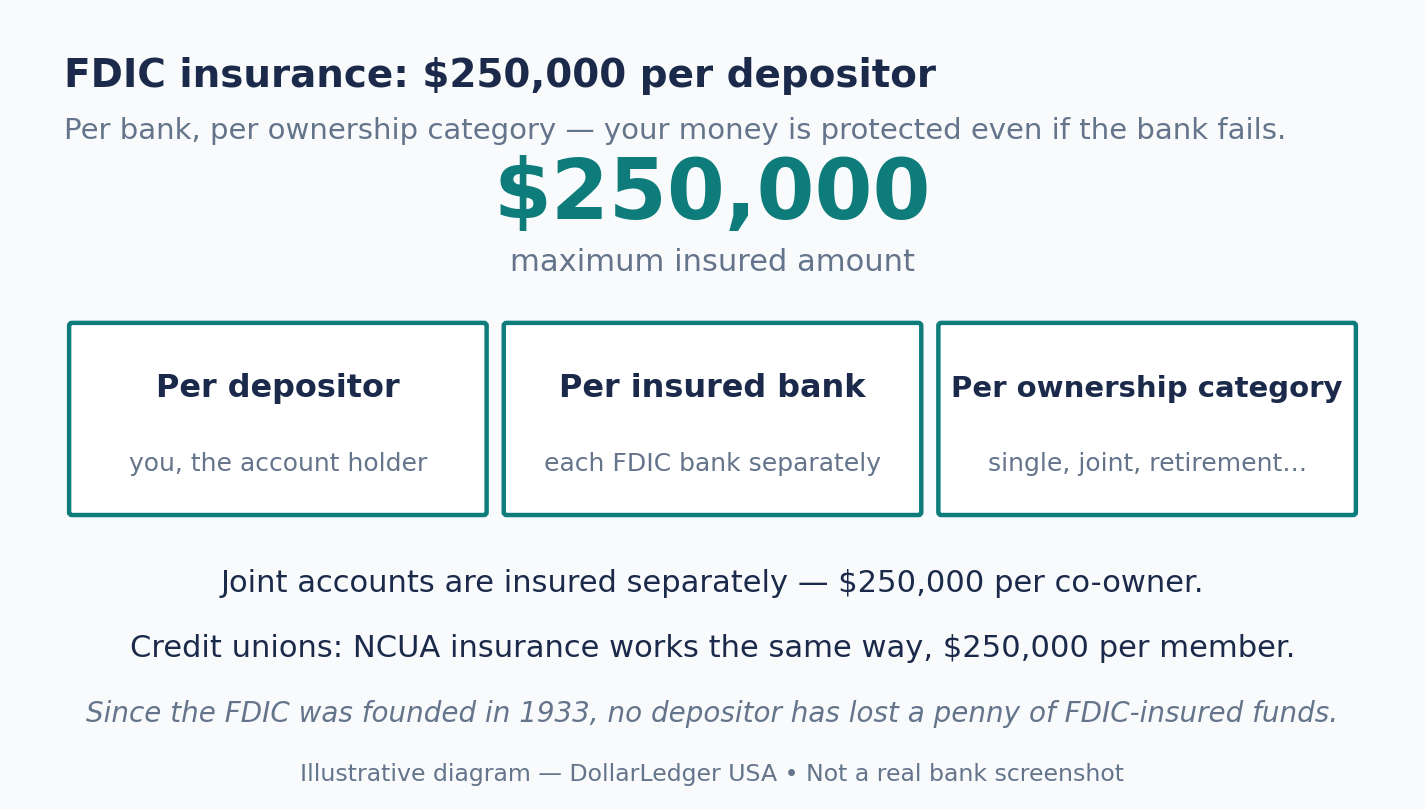
Illustrative diagram — FDIC insurance: $250,000 per depositor, per bank, per ownership category. NOT a real bank screenshot.
Step 5: Read the fine print — teaser rates, caps and fees
What to do: Read the conditions that decide what you earn.
How: Check four things: how long the rate lasts, what balance it covers, what you must do to keep it, and what the rate falls to after that. The best accounts have no monthly fees and no minimum balance — but some have a fee if you do not meet their terms.
Example: Axos ONE pays up to 5.00% APY for six months only, and only with $1,500 in checking and $1,500 monthly direct deposits. After that it falls to the standard rate.
Common mistake: Opening an account for a teaser rate and forgetting it. Set a reminder for the month the rate drops, then re-check.
Photo: A savings jar is a good habit. A high-yield account is the same habit, with interest. (Photo: Pexels)
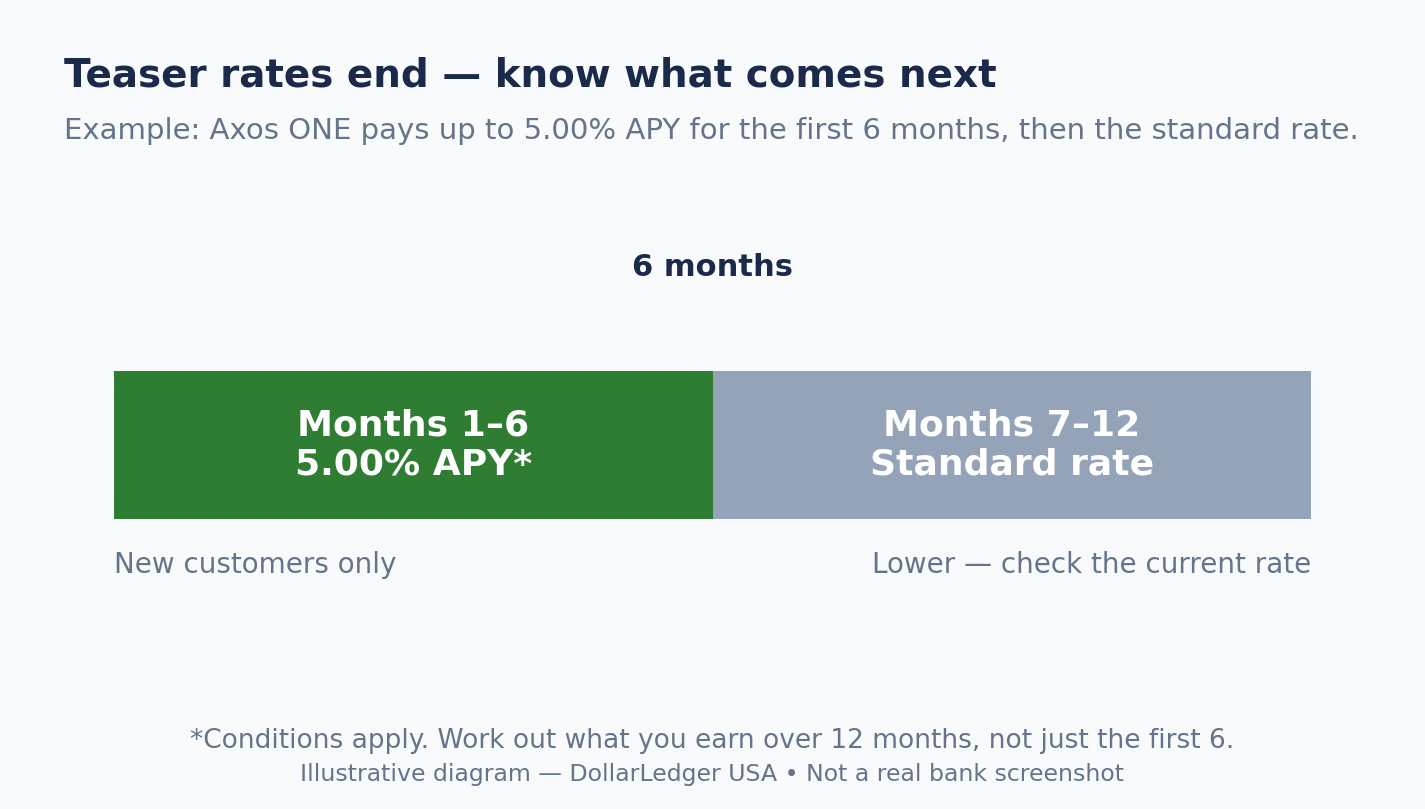
Illustrative diagram — Teaser rates end. NOT a real bank screenshot.
Step 6: Open the account and set it up right
What to do: Pick the account that fits you, open it, fund it, automate it.
How: Apply on the bank’s website with a photo ID, your Social Security number, and a transfer from your old account. Online banks ask the same questions as a local bank. Then set up an automatic transfer for every payday, so you save without thinking.
Example: Sarah moves $5,000 from her old 0.38% account to a 4.40% account, plus a $200 transfer every payday. After one year she earns about $220 from the new account, plus her regular deposits. In the old account she would have earned just $19 on the $5,000.
Common mistake: Closing your old account before the first transfer clears, or opening the new account without checking the teaser period first.
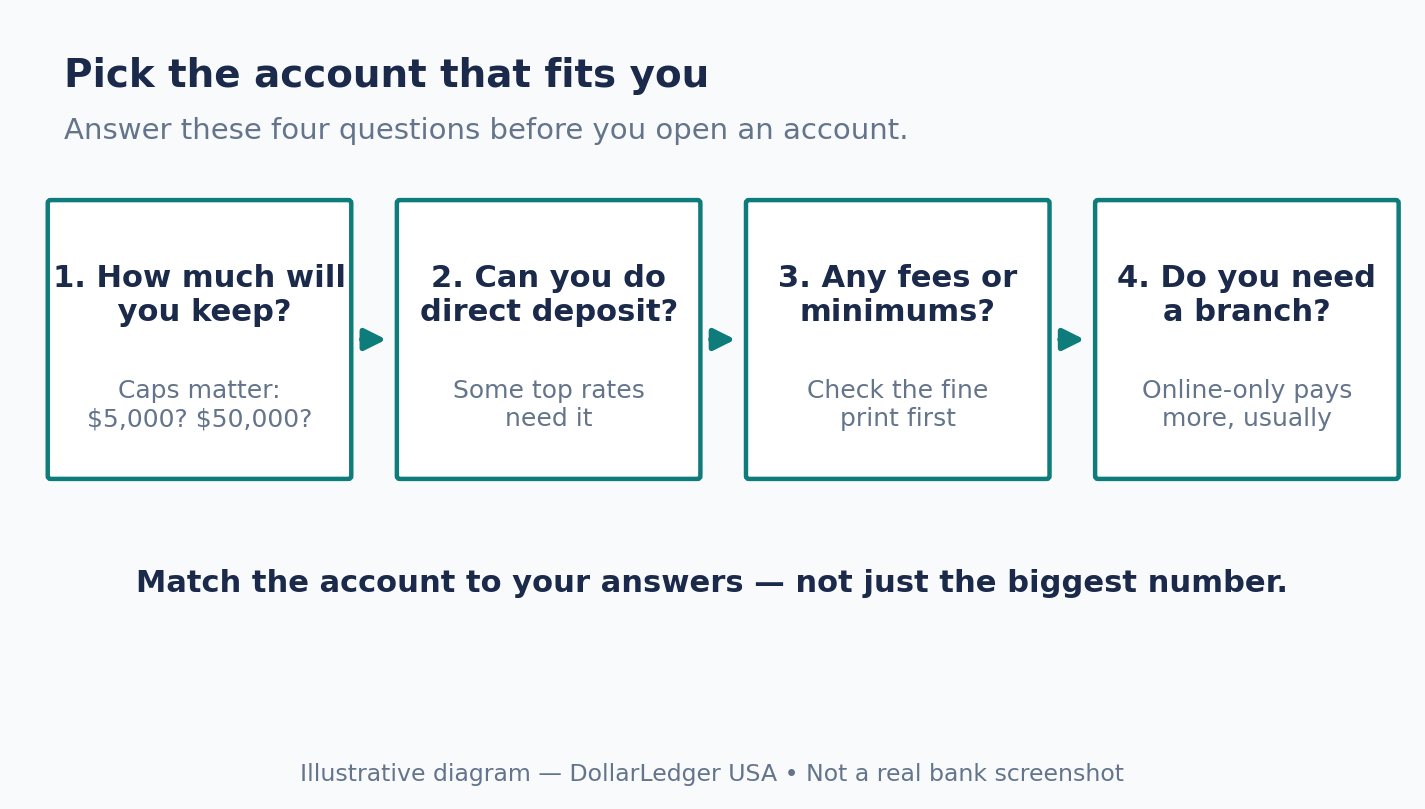
Illustrative diagram — Pick the account that fits you, not just the biggest number. NOT a real bank screenshot.
Checklist
- ☐ I compared APY with APY.
- ☐ I read the conditions: caps, teaser length, direct deposit rules.
- ☐ I checked the bank is FDIC- or NCUA-insured.
- ☐ I know what I earn after any teaser rate ends.
- ☐ I set up an automatic transfer for every payday.
- ☐ I set a reminder to re-check my rate in 6 months.
FAQ
What is a good APY for a savings account in 2026?
The national average is 0.38% APY. Top accounts pay around 4% to 5% APY. Anything above 4% is strong — and it is about ten times the average.
Is my money safe in an online bank?
Yes, if the bank is FDIC-insured. Deposits are protected up to $250,000 per depositor, per bank, per ownership category.
Can I lose money in a high-yield savings account?
No. A savings account is not an investment, so your balance never drops with the market. It only grows.
How fast can I get my money out?
Transfers to a linked bank usually take 1 to 3 business days. Keep a little money in checking for same-day needs.
Do I pay tax on the interest I earn?
Yes. Interest is taxable income. Your bank sends a Form 1099-INT if you earn $10 or more in a year.
Sources
- Motley Fool, “Best High-Yield Savings Accounts Today, Nov. 2, 2026” — rates, national average 0.38% APY, FDIC $250,000 limit: https://www.fool.com/money/banking/savings-accounts/
- Motley Fool, Best Savings Accounts of November 2026 — top accounts and rate tables: https://www.fool.com/money/banking/savings-accounts/best-savings-accounts/
- FDIC, Deposit Insurance at a Glance — $250,000 per depositor, per bank, per ownership category: https://www.fdic.gov/resources/deposit-insurance/
- Bankrate, average savings interest rates — Bankrate survey average 0.59% APY as of Nov 2, 2026 (different from the FDIC national average of 0.38%): https://www.bankrate.com/banking/savings/average-savings-interest-rates/
- DollarLedger USA, Welcome post
All rates were checked November 2, 2026. Rates are variable and change without notice — confirm the current rate on the bank’s website before opening an account.
Disclaimer: This article is for education only, not financial advice. Rates change often — confirm the current rate with the bank before opening an account.