How to Invest in the S&P 500 in 2026 — A Beginner's Step-by-Step Guide
 DollarLedger Team
- 06 Nov, 2026
Ask ten personal finance writers where a beginner should put their first dollars and most will answer: a low-cost S&P 500 index fund. It is the simplest way to own a slice of about 500 of America’s largest companies — Apple, Microsoft, Nvidia, Amazon and hundreds more — for a fee so small it is almost hard to believe. You do not need to pick stocks, time the market, or have thousands of dollars. Here are the six steps, in the right order — all figures checked November 6, 2026.
Photo: One S &P 500 index fund buys you a slice of about 500 large American companies at once. (Photo: Pexels)
What You Will Learn
- What the S&P 500 is — and why you buy a fund
- Which account to use first: 401(k) match, Roth IRA, or brokerage
- How to pick a fund by its expense ratio
- How to buy your first shares, even with $1
- How to automate monthly investing and reinvest dividends
- What to do when the market falls
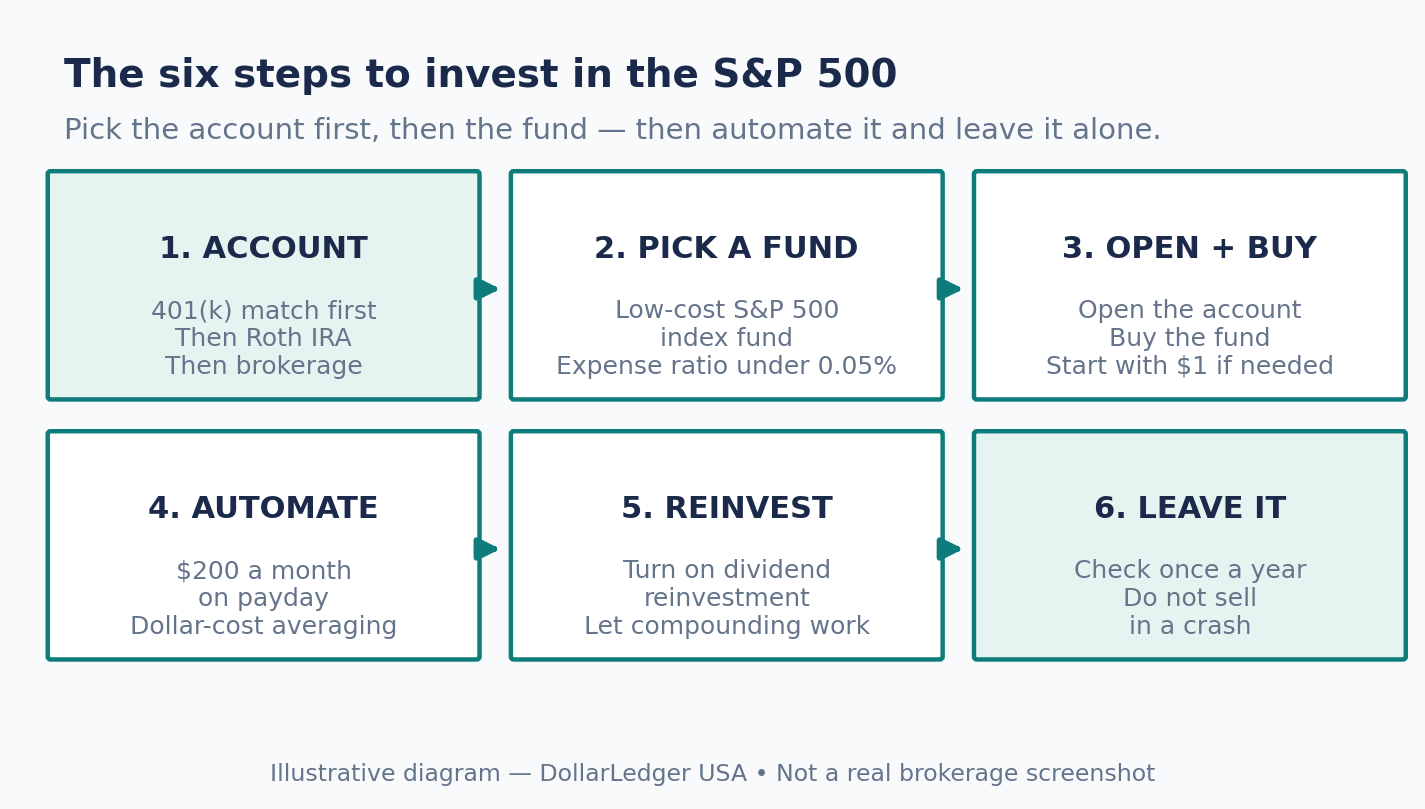
Illustrative diagram — The six steps to invest in the S &P 500 in 2026. NOT a real brokerage screenshot.
Step 1: Pick the account first
What to do: Pick the account first — it decides your tax bill.
How: Use this order. First, if your job offers a 401(k) match, contribute enough to get all of it — free money no investment can beat. The 2026 401(k) limit is $24,500 of your own pay, not counting the match. Second, open a Roth IRA: up to $7,500 for 2026, tax-free growth, tax-free qualified withdrawals in retirement. Third, once the Roth IRA is full, use a brokerage account — no yearly limit, but you pay tax on dividends and gains.
Example: Daniel earns $60,000; his employer matches 100% of the first 4% of his pay. He contributes 4% ($2,400 a year), gets another $2,400 free, then adds $300 a month to a Roth IRA in an S&P 500 fund.
Common mistake: Buying in a taxable brokerage account while leaving a 401(k) match unclaimed. The match is worth more than any fund choice.
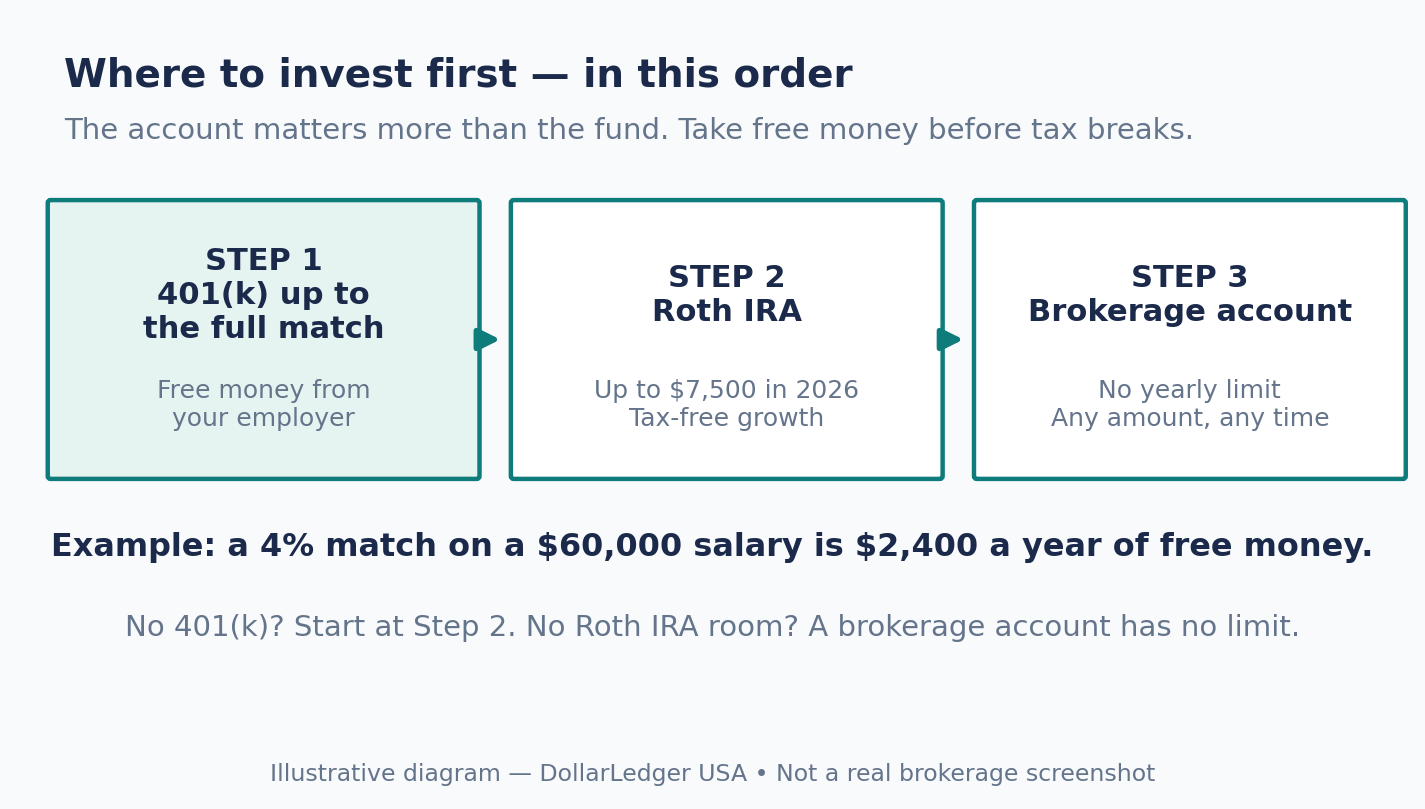
Illustrative diagram — Where to invest first: match, then Roth IRA, then brokerage. NOT a real brokerage screenshot.
Step 2: Pick a low-cost S&P 500 fund
What to do: Choose one S&P 500 fund with a tiny expense ratio.
How: You cannot buy the S&P 500 itself — an index is a list, not something you can own. You buy an index fund holding the same 500 stocks in the same proportions. Investor.gov, the SEC’s education site, explains that an index fund aims for approximately the same return as its index before fees. Since every S&P 500 fund holds nearly the same stocks, the fee is the main difference. The cheapest well-known options, as reported in October 2026, are Fidelity’s FXAIX at 0.015% ($1.50 a year per $10,000), Schwab’s SWPPX at 0.02% ($2), Vanguard’s VOO at 0.03% ($3), Vanguard’s VFIAX at 0.04% ($4) and the older SPY at 0.0945% ($9.45). VOO’s 0.03% was verified on Vanguard’s fund page on November 6, 2026. Any fund under 0.05% is fine — do not pay 1% for the same stocks.
Example: Sara holds $10,000 in VOO: $3 a year. Her coworker pays 1% — $100 a year — for almost the same stocks.
Common mistake: Paying a high fee because the fund came with an advisor or a fancy brand. The stocks are the same.
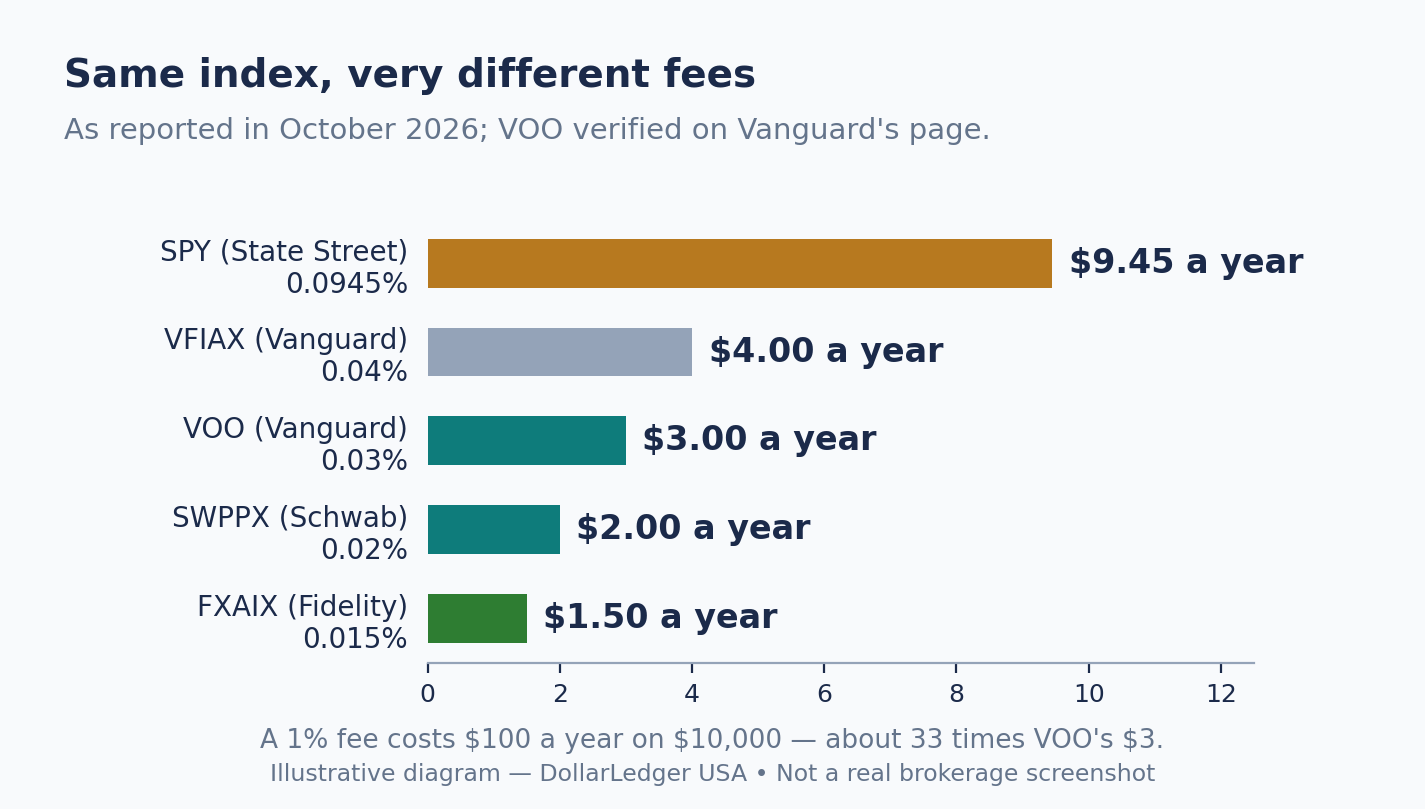
Illustrative diagram — Same index, very different fees. A 1% fee costs $100 a year on $10,000. NOT a real brokerage screenshot.
Step 3: Open the account and buy your first shares
What to do: Open the account and place your first buy.
How: Go to the provider’s website — Fidelity, Vanguard, or Charles Schwab — choose “Open an account” and pick the account type. You will need your Social Security number, a photo ID, and your bank details. Then search for your fund’s ticker — VOO, FXAIX, or SWPPX — and buy. One VOO share cost about $674 in early November 2026, but fractional shares at most major brokers let you start with $1. FXAIX or SWPPX take any dollar amount with no minimum at their home broker. Either way, you now own a slice of about 500 companies.
Example: Maya opens a Roth IRA at Fidelity with $100 and buys $100 of FXAIX — no minimum, no trading fee.
Common mistake: Opening the account and leaving the money as cash. Until you buy the fund, your money sits idle.
Photo: Opening an account takes about 15 minutes online — then buy the fund the same day. (Photo: Pexels)
Step 4: Automate it — invest the same amount every month
What to do: Set up an automatic monthly investment on payday.
How: This is dollar-cost averaging — the beginner’s best defence against bad timing. When prices are high, $200 buys fewer shares; when prices fall, it buys more. Over time you pay less than the average price. Pick an amount you can sustain — $100, $200, or $500 a month — and set the transfer for the day after payday. The habit matters more than the amount: $200 a month is $2,400 a year — $24,000 in 10 years before growth.
Example: Alex invests $200 a month. At $100 a share he gets 2 shares; at $50, 4 shares; at $75, 2.67 shares. He spent $600 for 8.67 shares — $69.23 a share, below the $75 average price.
Common mistake: Waiting for a “good time” to invest. Every month you wait is a month your money is not working.
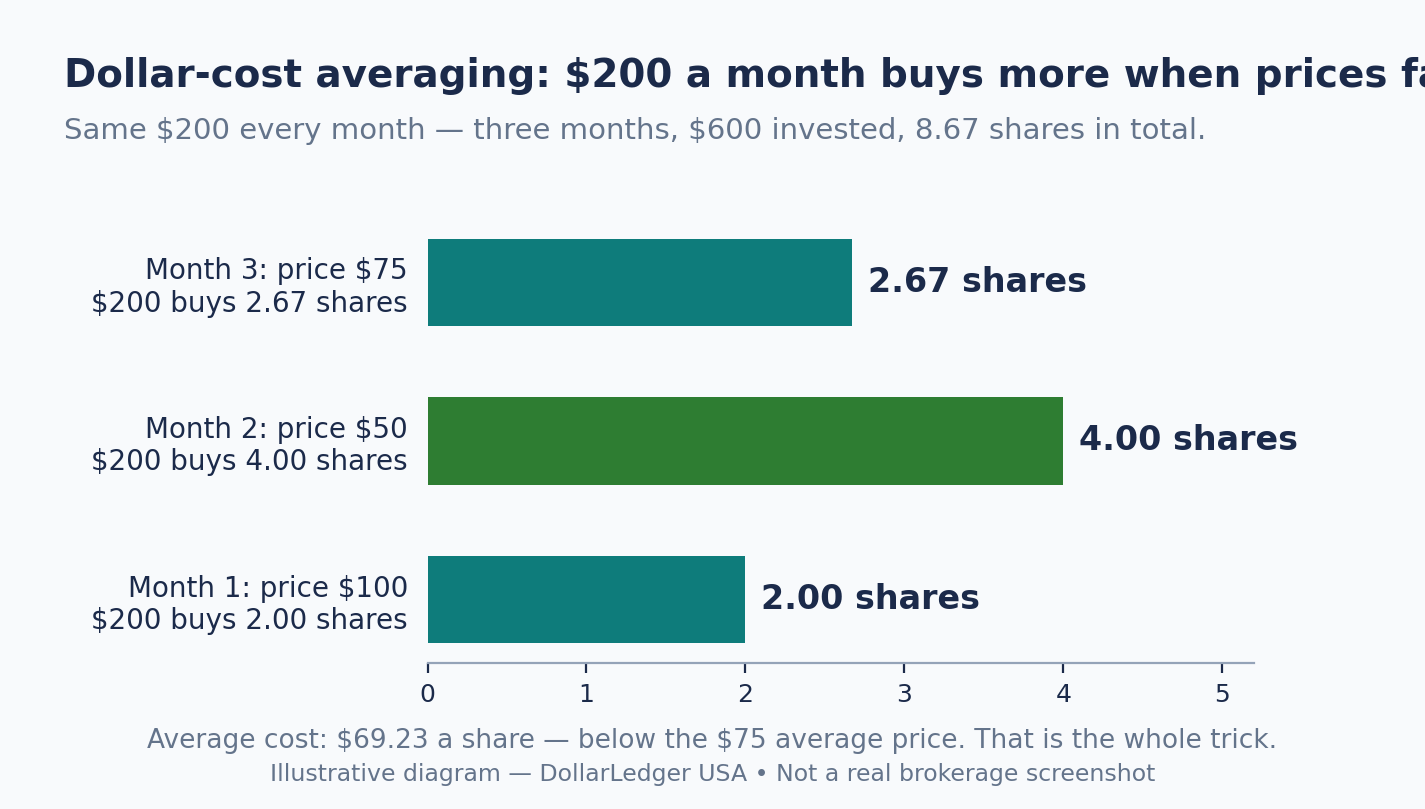
Illustrative diagram — The same $200 buys more shares when prices fall. NOT a real brokerage screenshot.
Step 5: Turn on dividend reinvestment and let compounding work
What to do: Turn on dividend reinvestment and give it time.
How: The 500 companies pay dividends — a share of their profits, usually every quarter. Your fund collects them and passes them to you. With dividend reinvestment on, those dividends automatically buy more shares instead of landing as cash, so your money compounds: your dividends earn dividends. Dividends have supplied roughly a third of the index’s long-run total return, reported. Now the honest part: the long-run average return is reported at about 10% a year before inflation (roughly 10% compounded from 1928 through 2025), or about 7% after inflation. That is an average, not a promise — in one year the market can rise 25% or fall 20%. For example, $10,000 at a steady 10% a year would reach about $174,494 in 30 years; at 7%, about $76,123; at 4%, about $32,434 — before fees and taxes.
Example: Warren Buffett’s instruction for his wife’s money (2013 Berkshire letter, reported): 90% in a very low-cost S&P 500 index fund, 10% in short-term government bonds.
Common mistake: Taking dividends as cash and spending them. Every dollar paid out stops compounding for you.
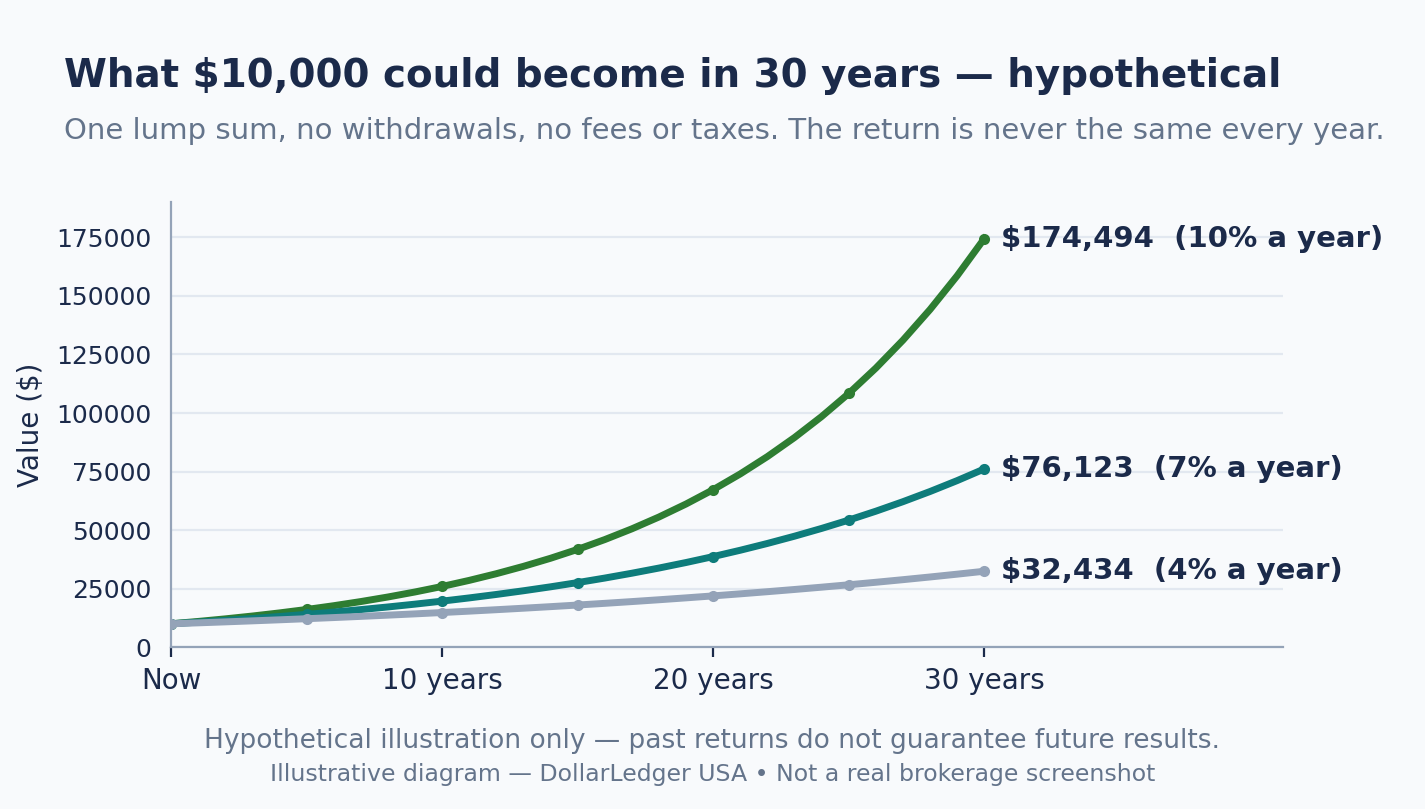
Illustrative diagram — Hypothetical growth of $10,000 over 30 years. NOT a real brokerage screenshot, and not a promise of future returns.
Step 6: Leave it alone — especially when the market falls
What to do: Check once a year; do not sell in a crash.
How: The S&P 500 falls hard sometimes. It lost more than half its value from its 2007 peak to its 2009 low, and fell about 19% in 2022 — both reported. Sellers locked in losses; steady investors bought cheap shares and were there for the recovery. Set two rules now. First, only invest money you will not need for five years — money you need soon belongs in a high-yield savings account, not stocks. Second, a falling market means your $200 buys more shares, not that it is time to sell.
Example: In 2022 the index fell about 19%. Priya kept her $200 a month going all year and her account recovered with the market instead of locking in a loss.
Common mistake: Checking your balance every day and selling after a bad week. Daily prices are noise; the plan works over decades.
Photo: Markets fall as well as rise — the plan is built for decades, not days. (Photo: Pexels)
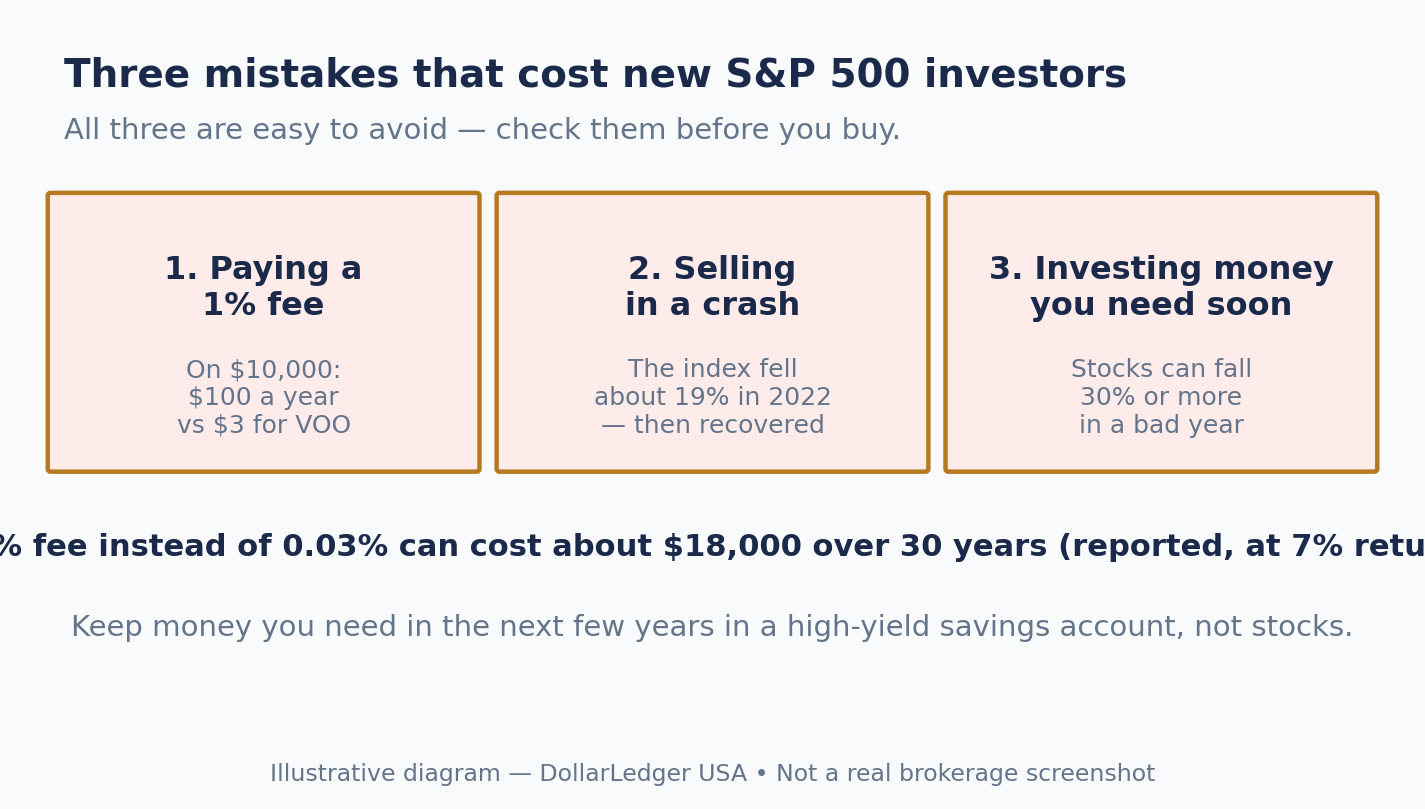
Illustrative diagram — Three mistakes that cost new S &P 500 investors. NOT a real brokerage screenshot.
Checklist
- I picked my account in the right order: 401(k) match, then Roth IRA, then brokerage.
- I chose one S&P 500 fund with an expense ratio under 0.05%.
- I opened the account and bought the fund — no cash sitting idle.
- I set up an automatic monthly investment on payday.
- I turned on dividend reinvestment.
- I will only invest money I do not need for five years, and I will not sell in a crash.
FAQ
Can I buy the S &P 500 directly? No — the S&P 500 is an index, a list of about 500 large US companies, not something you can buy. You buy a fund that tracks it, such as VOO, FXAIX, or SWPPX.
How much money do I need to start investing in the S &P 500? As little as $1 at many brokers, thanks to fractional shares. FXAIX and SWPPX have no minimum at their home broker.
Is the S &P 500 a safe investment? It is diversified across about 500 companies, so no single company can sink it — but it is not safe in the short term. It can fall 20% or more in a bad year. Only invest money you will not need for five years.
ETF or mutual fund — which S &P 500 fund should I choose? Both hold the same stocks — pick by account. In a 401(k) or IRA, a mutual fund like FXAIX or SWPPX is simplest. In a taxable account, an ETF like VOO is slightly more tax-efficient. Keep the fee under 0.05%.
Sources
- SEC Investor.gov — “Index Fund”: what an index fund is: https://www.investor.gov/introduction-investing/investing-basics/glossary/index-fund
- Vanguard — VOO: tracks the S&P 500 Index, expense ratio 0.03% as of April 28, 2026: https://advisors.vanguard.com/investments/products/VOO
- DollarLedger USA, “Roth IRA Contribution Limits 2026” — the $7,500 limit in Step 1: </blog/roth-ira-contribution-limits-2026-how>
All figures checked November 6, 2026.
This article is for education only, not financial advice. Investing involves risk, including losing money. Confirm current fees and limits on the provider’s page before investing.